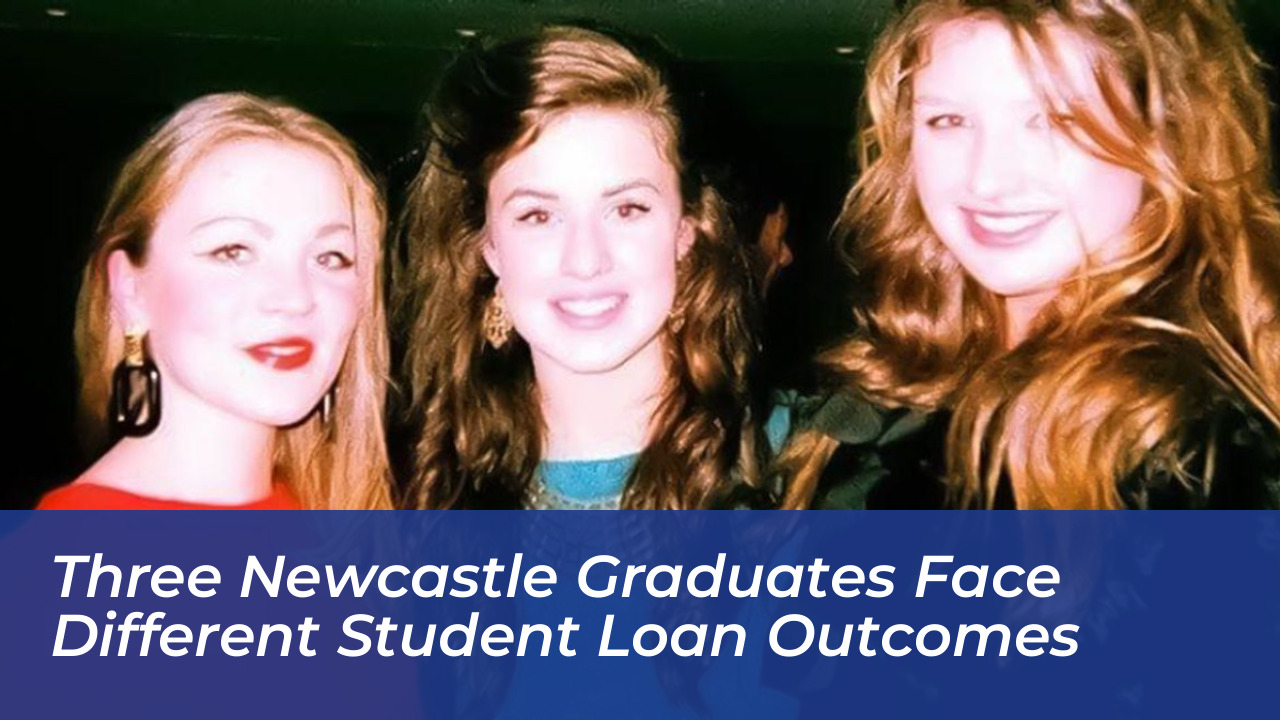
Three friends who attended the University of Newcastle have experienced sharply different financial outcomes from Britain’s Plan 2 student loan system. This highlights a growing debate over rising interest rates and repayment rules. Lizzy, Libby, and Charlotte began university in 2012, borrowing approximately £37,500 each to cover tuition fees and living costs. Today, their contrasting balances and repayment trajectories reflect how career paths and salaries shape long-term debt under a framework that continues to face intense public scrutiny.
The experiences of the three friends emerge as the UK government confronts mounting pressure to reform student financing. Research published in February by the Institute for Fiscal Studies (IFS) indicates that graduates with a £50,000 Plan 2 balance generally need to earn roughly £63,000 or more just for their underlying debt to begin decreasing. Under government adjustments announced in November, the income threshold for repayments is set to remain frozen for three years. This change means graduates will begin repaying sooner and contributing larger monthly sums.
Diverging Paths a Decade After Graduation
When Lizzy, Libby, and Charlotte met as freshers in 2012, tuition fees in England and Wales had tripled to £9,000 per year, coinciding with the launch of the Plan 2 loan scheme. Ten years since the first cohort began repayments, the friends have found their financial realities moving in opposite directions despite starting from the exact same point.
Charlotte, now a physiotherapist working in the private sector in Bristol after completing a master’s degree and working in the NHS, earns about £50,000. Despite making regular contributions, she has seen her debt grow. “Since April this year, I’ve paid off in the region of £450 and I’ve accrued over £500 in interest,” she notes, describing the situation as disheartening.
Libby, who works as a project manager in a housing association in Worcester, earns £72,000. Her balance has hovered around £47,000 for years. Currently on maternity leave, she acknowledges that interest will continue to accrue while her earnings-and corresponding monthly repayments-temporarily drop. “It feels like I will never pay it off,” she explains.
Meanwhile, Lizzy pursued a career in financial services in Bristol and achieved the highest earnings among the group at £85,000 a year. Deciding last year to clear her student debt entirely by borrowing from family, she avoided years of accumulating interest, estimating she saved roughly £20,000. While financial experts like MoneySavingExpert founder Martin Lewis warn that voluntary overpayments only benefit high earners, Lizzy describes her move as a calculated gamble that bought her long-term freedom from the system.
Broader Pressures and Calls for Reform
The challenges faced by the Newcastle graduates mirror a wider national discussion surrounding student loan affordability. Campaign groups such as Rethink Repayment argue that Plan 2 borrowers-who face interest rates pegged to the Retail Prices Index (RPI) plus up to 3% depending on salary-are unfairly burdened while trying to secure housing, start families, and save for retirement.
Critics have also pointed to historical messaging from authorities. Last year, parliamentary inquiries and investigations scrutinized past school presentations that compared monthly student loan deductions to low-cost phone contracts, a practice critics and MPs characterized as misleading for higher-earning graduates.
In response to ongoing criticism, the Department for Education (DfE) stated that it is taking decisive steps to improve the student finance system, noting recent adjustments to maintenance loans and the raising of repayment thresholds. Nevertheless, as outstanding student loan debt across England climbs past hundreds of billions of pounds, borrowers and campaigners continue to demand structural changes to ensure long-term fairness.
Frequently Asked Questions
What is a Plan 2 student loan?
Plan 2 student loans were introduced in England and Wales in 2012 for undergraduate students starting higher education when tuition fees rose up to £9,000 per year. Outstanding balances are written off after 30 years.
Why do some graduates owe more than they borrowed?
Because interest rates are calculated using the Retail Prices Index (RPI) plus an additional percentage based on income, many graduates’ monthly payments do not cover the accumulating interest, causing the overall balance to rise over time.
What income threshold triggers Plan 2 repayments?
Graduates repay 9% of their earnings above the specified repayment threshold, which has been subject to government freezes that require lower earnings boundaries before deductions begin.
Can graduates make voluntary overpayments to clear their debt early?
Yes, borrowers can make voluntary lump-sum repayments. However, financial experts advise that this generally only benefits very high earners who can clear the balance quickly, as smaller overpayments may simply waste money on interest that would otherwise be written off.
Are student loans written off after a certain period?
Yes, any remaining Plan 2 student loan balance is automatically written off 30 years after the April following the student’s graduation date.