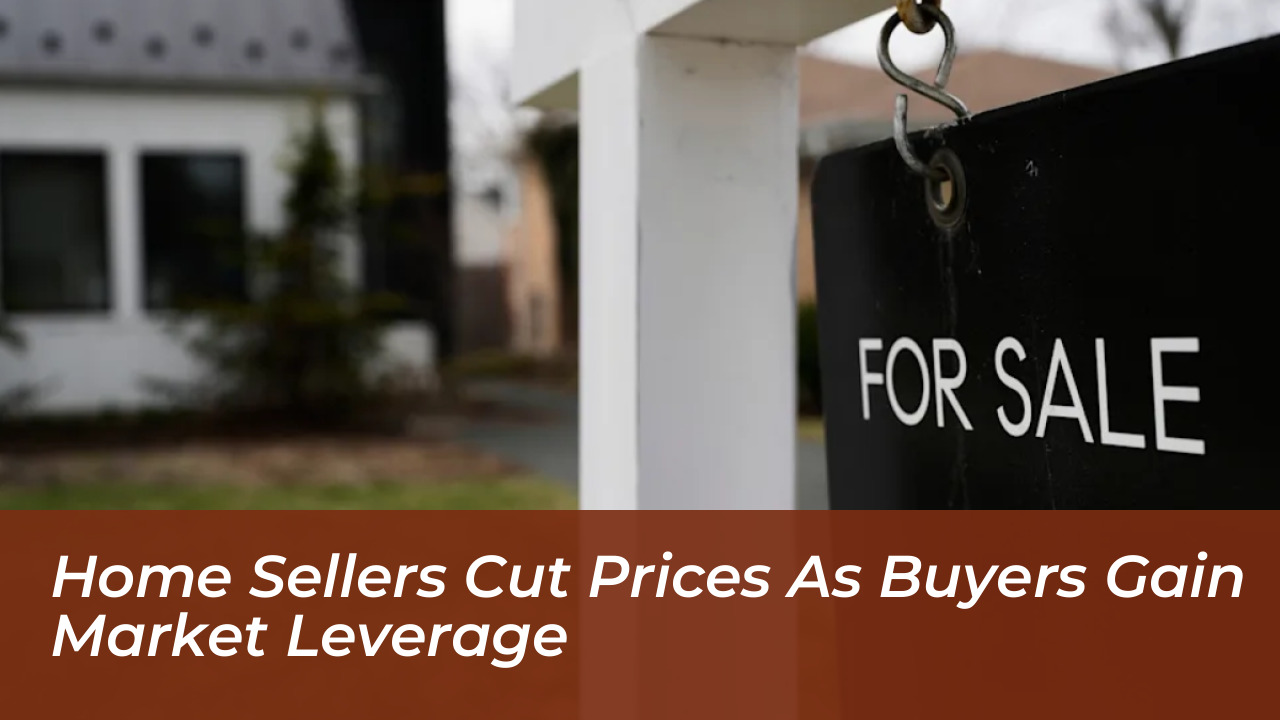

Home sellers across the United States are facing extended wait times and heightened financial pressure. Elevated mortgage rates, persistent inflation, and years of accumulated property price growth are discouraging potential purchasers. With sellers currently outnumbering prospective buyers by a wide margin, many homeowners are forced to lower asking prices. They are also offering thousands of dollars toward closing costs or repair expenses to finalize transactions, according to industry real estate data.
This dramatic shift marks a stark contrast to the buying frenzy earlier in the decade. Back then, exceptionally low mortgage rates drove fierce competition and frequently pushed final sale prices well above initial asking prices. Today, rising borrowing costs, surging home prices, and a cautious economic outlook have made homeownership significantly less affordable. This drives many buyers to postpone purchases until conditions improve.
The Shift to a Buyer’s Market
According to a recent analysis by Redfin, sellers outnumber buyers by roughly 63% across the 50 largest U.S. metropolitan areas. The total count of active buyers recently dipped to approximately 929,000-representing the lowest level on record dating back to 2013. Meanwhile, the inventory of active sellers surged to its highest mark since 2020.
Mark Fleming, chief economist at First American Financial, noted that the current environment has firmly reestablished a buyer’s market. Sellers are frequently stuck between difficult choices: aggressively cut prices and offer buyer concessions to move properties quickly, or hold out longer, even if doing so delays major personal and professional plans.
National median home listing prices dropped 1.2% in September from the previous year down to $419,250. This marked the 11th consecutive month of year-over-year declines, according to Realtor.com. During the same period, roughly 21% of all active U.S. listings underwent initial price reductions, hitting a four-year high.
Real-World Impacts on Homeowners
The stagnant housing market has left many homeowners in limbo. They are unable to relocate for employment opportunities, downsize or upsize to accommodate changing family needs, or execute other major life milestones.
For Liz Suder, a 56-year-old finance director from Murphy, Texas, the selling process took much longer than anticipated. Having owned her four-bedroom home for 21 years, she initially listed the property for $750,000 in April of last year to find a smaller space now that her children have grown. After months without success, she briefly pulled the home off the market before relisting it at lower figures. She finally secured a buyer at $650,000-a full $100,000 below her original asking price-while also sweetening the agreement by contributing $9,000 toward necessary repairs.
Similarly, Rick Ganga, an operations manager in Blaine, Washington, has experienced firsthand the challenges of a stalled regional market. Bound by a divorce decree requiring the sale of his home, Ganga listed his three-bedroom property for $825,000 on June 1. Despite subsequent price reductions approaching the $800,000 threshold, low traffic and zero offers have stalled his plans to transfer to another state with his company.
“That’s not anything I’m going to entertain,” Ganga said regarding deeper price cuts that would exceed his accumulated equity built since purchasing the property in 2022. “It doesn’t make sense.”
Mortgage Rates and Affordability Hurdles
The primary driver behind the market slowdown remains the rapid upward trajectory of borrowing costs. After briefly dipping below 6% earlier in the year, the average rate on a 30-year fixed mortgage surged as high as 7.4%, touching its highest level in nearly three years. This sustained pressure has severely stifled transactional volume nationwide.
Higher rates are simultaneously granting buyers unprecedented leverage to demand financial assistance. Beyond straightforward price drops, shoppers routinely request seller credits to buy down mortgage interest rates for the initial years of the loan or cover closing costs entirely.
“It’s sort of like an indicator of where the market is right now, with buyers gaining leverage at the expense of sellers, and sellers doing more now to meet buyers halfway,” explained Jake Krimmel, a senior economist at Realtor.com.
While these concessions offer vital financial relief to active shoppers, experts note they may still fall short of overcoming the overarching affordability barriers keeping millions of prospective buyers sidelined. As the market transitions into subsequent seasons, homeowners capable of pulling their listings are increasingly choosing to wait out the economic turbulence. This leaves active sellers to compete aggressively for a much smaller pool of qualified purchasers.