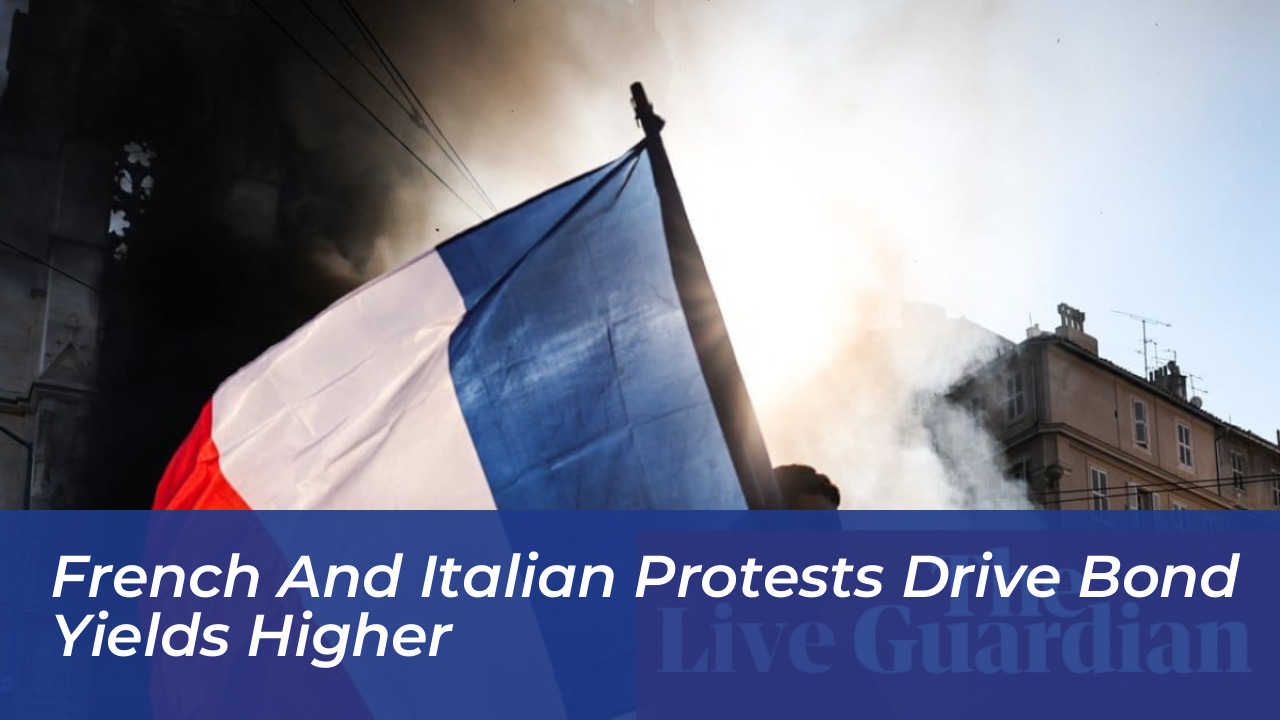

Violent protests over rising living costs in France and severe shortages of fuel and food in Italy have heavily unsettled European financial markets. The social unrest has sent European stocks lower, pushed government bond yields significantly higher, and weakened the euro as investors grow increasingly alarmed by mounting public debt and political instability.
The market reaction reflects deep-seated concerns regarding France’s deteriorating public finances and the potential spread of debt pressures across the entire eurozone. As investors actively sold off French government assets, the euro fell nearly 0.4% against the U.S. dollar, trading down to $1.1201.
Surging French Bond Yields and Widening Spreads
According to market data cited by The Guardian, the yield on France’s 10-year government bond climbed by as much as 8 basis points to reach 4.86%. In sharp contrast, Germany’s 10-year benchmark yield remained flat at 3.41%, highlighting the widening divergence in perceived risk between core eurozone economies.
The yield spread-the difference between French and German 10-year government bonds-widened to 145 basis points, marking its highest level in two years. However, this remained just below the nearly 160 basis points recorded in early October, when the French 10-year yield touched 4.99%, its highest level since 2002.
Market analysts note that foreign investors hold a growing share of French debt, with overseas ownership rising from roughly 48% at the start of 2022 to nearly 60% by early 2026. This high level of foreign participation leaves the French bond market exceptionally vulnerable to volatility during risk-off economic environments.
Political Instability and Fiscal Challenges
The financial market turbulence coincides with intense social unrest. Hundreds of thousands of citizens marched across France over the weekend to protest political paralysis, declining living standards, and the deteriorating state of public services, including healthcare and education. Demonstrations in major cities such as Paris, Lyon, and Marseille turned violent, resulting in property destruction, clashes with police, and more than 2,000 arrests.
Investors are increasingly questioning whether Prime Minister Sébastien Lecornu’s minority government can successfully pass the upcoming 2027 budget and implement a credible path to reduce the nation’s soaring budget deficit, which currently hovers around 5% of GDP-well above the European Union’s 3% limit.
Broader Eurozone Implications
While Italy has historically been viewed as the primary risk factor in European sovereign debt markets, recent improvements in Rome’s fiscal discipline and political stability have partially shifted investor anxiety northward. France has effectively replaced Italy as Europe’s primary bond market concern.
Financial experts warn that if political gridlock persists and fiscal reforms are blocked by public resistance, borrowing costs for French companies and households will continue to climb, testing the resilience of the broader European financial architecture.