Global financial markets experienced a sharp reversal on September 25, 2026, as the Dow Jones Industrial Average climbed 450 points in a powerful risk-on rally. This sudden advance provided welcome relief to equity investors who had spent previous sessions navigating intense volatility, restrictive monetary policy, and rising sovereign bond yields. The catalyst for this dramatic shift stemmed from unexpected diplomatic breakthroughs between the United States and Iran, which dramatically reduced geopolitical risk premiums. By easing tensions in a historically volatile region, the peace talks shifted market focus away from persistent macro headwinds and toward renewed economic stability.
- Wall Street Rebound: Dow Climbs 450 Points
- Overview of the September 25 Market Session
- Price-Weighted Dynamics of the Dow
- Geopolitical De-Escalation: The US and Iran Breakthrough
- Diplomatic Progress and Regional Stability
- Securing the Strait of Hormuz
- Navigating Fixed-Income Headwinds and Treasury Yields
- Benchmark 10-Year Yields Reach Multi-Year Highs
- Long-Term Debt Pressure in 30-Year Bonds
- Macroeconomic Indicators: PCE Inflation and Labor Markets
- Employment Data and Growth Durability
- Sticky Personal Consumption Expenditures (PCE) Metrics
- Impact on Commodity Markets and Energy Equities
- Crude Oil Price Adjustments
- Sector Rotation Across Blue-Chip Stocks
- Strategic Portfolio Management Amid Shifting Market Regimes
- Balancing Fixed-Income Yields and Equities
- Frequently Asked Questions
- Why did the Dow Jones Industrial Average surge 450 points on September 25, 2026?
- How does the Strait of Hormuz impact global stock markets?
- Are high Treasury yields still a concern for Wall Street?
Wall Street Rebound: Dow Climbs 450 Points
Overview of the September 25 Market Session
The 450-point advance in the Dow Jones Industrial Average marked a stark contrast to the negative sentiment that defined the September 24 trading session. Just 24 hours prior, Wall Street stumbled as market participants fixated on restrictive interest rates and sticky inflation metrics. Selling pressure dominated major exchanges, pushing down equity valuations and fueling anxiety over long-term corporate borrowing costs.
Everything changed on September 25 as aggressive institutional buying flooded the market. The aggressive capital allocation lifted all major equity benchmarks. The S&P 500 rebounded sharply, the Nasdaq Composite shrugged off high Treasury yields to post solid gains, and the small-cap Russell 2000 captured renewed interest from investors hunting for domestically focused growth opportunities.
Price-Weighted Dynamics of the Dow
Because the Dow Jones Industrial Average relies on a price-weighted structure rather than market capitalization, high-priced blue-chip components exerted a massive influence on the 450-point gain. Industrial conglomerates, multinational technology leaders, and consumer discretionary giants spearheaded the advance. As geopolitical fears receded, buyers targeted companies with robust balance sheets and extensive international supply chains.
This concentrated buying power demonstrated how quickly market participants pivot when tail risks disappear. Industrial firms within the index benefited directly from lower energy input projections, while retail and consumer goods providers enjoyed a boost from improving consumer sentiment metrics.
Geopolitical De-Escalation: The US and Iran Breakthrough
Diplomatic Progress and Regional Stability
The primary driver behind the September 2026 market rally centered on high-level negotiations between American and Iranian representatives. Both nations engaged in focused diplomatic frameworks designed to end regional military confrontations that had threatened international trade lanes for months. The prospect of a lasting peace accord eliminated severe tail risks that previously hung over global commerce.
Investors responded rapidly by reallocating capital back into equities. Removing the threat of prolonged military escalation reduced uncertainty for multinational corporations operating in the Middle East and surrounding trade corridors. This newfound diplomatic stability allowed fund managers to reprice risk downward across multiple asset classes.
Securing the Strait of Hormuz
Central to these peace talks was a concrete framework to fully reopen and secure the Strait of Hormuz. This vital maritime chokepoint handles approximately 20 percent of world petroleum consumption. Previous disruptions along this crucial transit route had inflated global crude prices and stoked international supply chain anxieties.
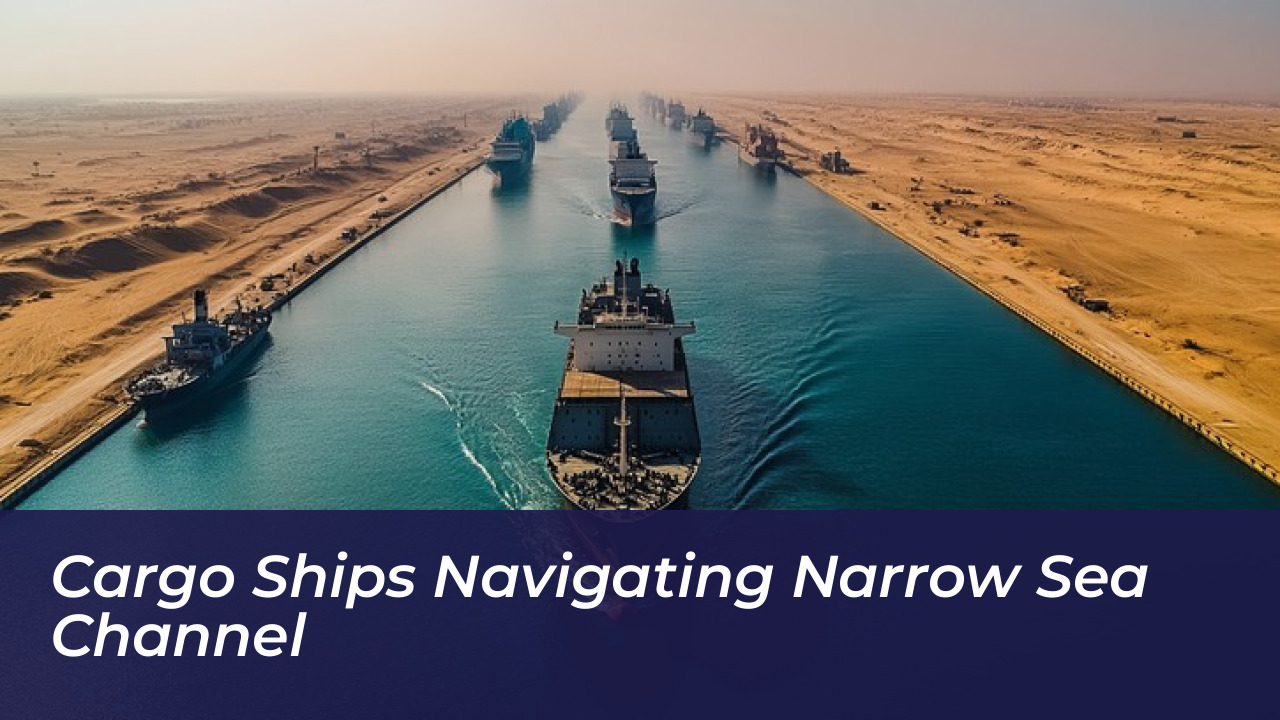
News of progress toward restoring unhindered commercial transit immediately cooled energy markets. By preventing a major cost-push inflation shock, the diplomatic breakthrough protected corporate profit margins across manufacturing, transportation, and agricultural sectors. Lower energy security risks provided the foundational relief that allowed equity indices to surge.
Navigating Fixed-Income Headwinds and Treasury Yields
Benchmark 10-Year Yields Reach Multi-Year Highs
This stock market surge occurred against a backdrop of restrictive fixed-income conditions that normally depress equity valuations. Prior to the diplomatic breakthrough, the benchmark U.S. 10-year Treasury yield surged to its highest level since 2007. Elevated sovereign yields increase corporate borrowing costs and reduce the present value of future earnings.
Equity buyers initially pulled back as yields breached critical technical resistance levels. However, the sheer magnitude of the geopolitical relief overshadowed fixed-income constraints during the September 25 session. Traders temporarily looked past debt market pressures to price in lower commodity costs and improved global economic visibility.
Long-Term Debt Pressure in 30-Year Bonds
Long-term sovereign debt faced persistent liquidation alongside the 10-year benchmark. Yields on 30-year Treasury bonds reached multi-decade highs as investors demanded higher term premiums. These adjustments reflected expanded federal deficit projections and stubborn price pressures across the broader economy.
Even with long-term borrowing costs climbing, equity markets demonstrated resilience. The prospect of lower geopolitical friction outweighed the immediate drag from high sovereign yields, proving that risk appetite often dictates short-term market direction over pure fixed-income math.
Macroeconomic Indicators: PCE Inflation and Labor Markets
Employment Data and Growth Durability
The diplomatic breakthroughs coincided with vital macroeconomic data releases that clarified underlying U.S. economic health. The U.S. Department of Labor published employment and nonfarm payroll reports showing healthy labor demand without triggering runaway wage inflation. Moderate job growth reaffirmed that corporate profit margins remain secure.
This balanced economic expansion helps stave off near-term recession fears. Investors welcomed the data because it indicated a resilient economy capable of supporting stable corporate earnings through the final quarters of 2026 and into 2027.
Sticky Personal Consumption Expenditures (PCE) Metrics
At the same time, the Bureau of Economic Analysis released the latest Personal Consumption Expenditures index. Core PCE readings confirmed that inflation remains persistent and sits above the Federal Reserve official two percent target. While sticky inflation limits the central bank capacity for aggressive interest rate cuts, the alignment of steady employment with moderate economic growth prevented market panic.
| Economic Metric | Latest Reading (Sept 2026) | Market Impact |
|---|---|---|
| Dow Jones Industrial Average | +450 Points (+0.93%) | Sharp risk-on recovery across industrial and retail equities |
| 10-Year U.S. Treasury Yield | Multi-Year Peak (Highest since 2007) | Created headwinds for corporate borrowing and valuations |
| 30-Year U.S. Treasury Yield | Multi-Decade High | Pushed mortgage and long-term capital costs upward |
| Strait of Hormuz Status | Negotiation for Reopening | Drove immediate downward pressure on global crude futures |
Impact on Commodity Markets and Energy Equities
Crude Oil Price Adjustments
Commodity trading desks reacted swiftly to news of diplomatic progress in the Middle East. Both Brent crude and West Texas Intermediate futures experienced immediate downward pressure as supply risk premiums evaporated. This price correction provided substantial relief for commercial aviation, global logistics providers, and everyday consumer transportation.
Lower energy input expenses directly improve the bottom line for transport-heavy industries. By reducing the threat of an oil shock, the peace talks removed a primary driver of goods inflation that had plagued central banks for years.
Sector Rotation Across Blue-Chip Stocks
Market participants initiated noticeable sector rotations following the energy price drop. Capital reallocated away from pure-play energy producers and flowed into broader industrial, financial, and consumer retail equities. Improved earnings visibility for late 2026 and early 2027 encouraged investors to diversify holdings across cyclical and growth sectors alike.
Strategic Portfolio Management Amid Shifting Market Regimes
Balancing Fixed-Income Yields and Equities
Managing portfolios in the current market environment requires careful navigation between attractive fixed-income yields and volatile equity valuations. Investors must balance the security of multi-year high Treasury bonds against the growth potential found in blue-chip equities.
Adopting disciplined risk management techniques helps mitigate sudden sentiment reversals. When geopolitical headlines can swing major indices by hundreds of points within a 24-hour window, maintaining diversified asset allocations remains the best defense against unexpected market shocks.
Frequently Asked Questions
Why did the Dow Jones Industrial Average surge 450 points on September 25, 2026?
The 450-point surge occurred primarily due to positive diplomatic developments between the United States and Iran. These peace talks aimed to ease Middle Eastern tensions and secure the Strait of Hormuz, removing major geopolitical risk premiums and lowering energy market anxieties.
How does the Strait of Hormuz impact global stock markets?
The Strait of Hormuz handles roughly 20 percent of global petroleum consumption. Threats to this vital chokepoint drive crude oil prices higher, creating cost-push inflation across transportation, manufacturing, and consumer goods. Securing the waterway lowers energy costs and boosts corporate earnings visibility.
Are high Treasury yields still a concern for Wall Street?
Yes. Although equity traders temporarily looked past fixed-income pressures to celebrate geopolitical de-escalation, benchmark 10-year Treasury yields sitting near 2007 highs continue to create borrowing cost headwinds for corporations.