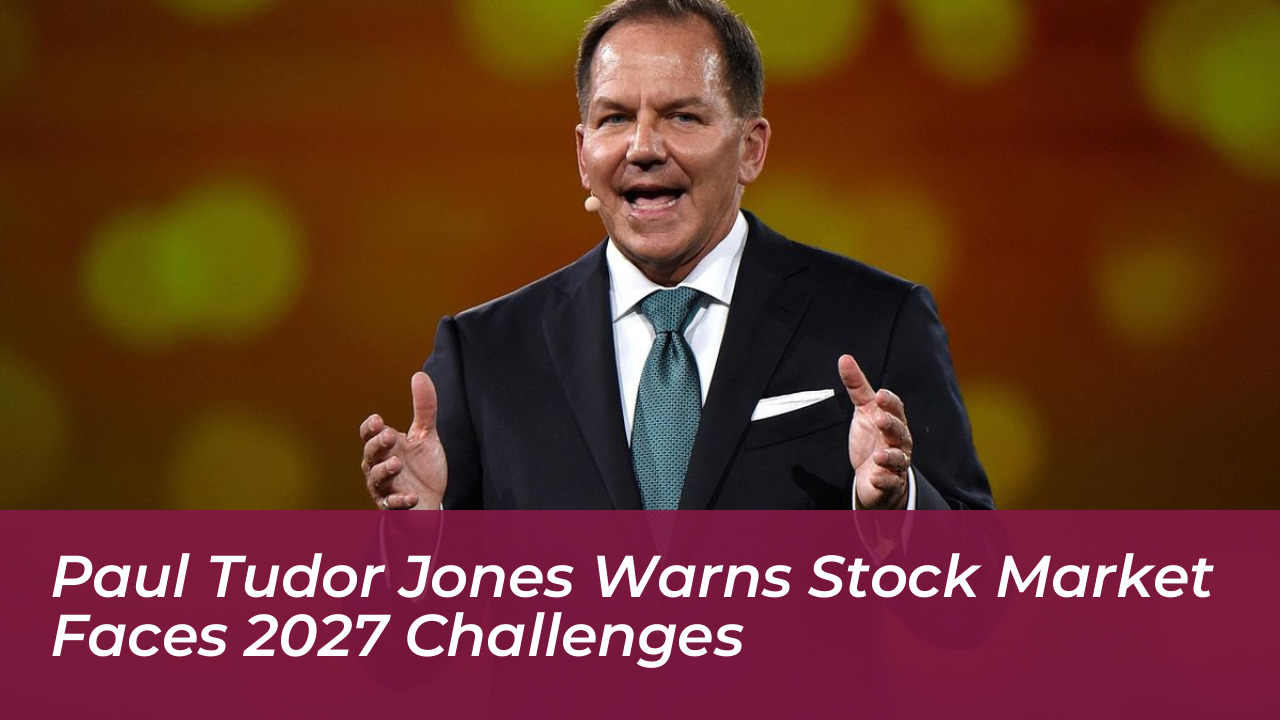
Veteran hedge fund manager and Tudor Investment founder Paul Tudor Jones warned on Tuesday that the U.S. stock market could face extraordinary challenges by 2027. Speaking on CNBC’s “Squawk Box,” Jones pointed to a major shift in equity supply and investor demand. This shift, driven heavily by artificial intelligence capital requirements, threatens to disrupt the four-year market rally.
According to Jones, the market is heading toward the most negative flow picture it has experienced since 2002. For much of the recent bull run, corporate buybacks and merger-and-acquisition activity acted as tailwinds. They steadily shrank the total supply of shares available to the public. However, that dynamic is now reversing as massive technology companies prepare to flood the market with new equity.
AI Capital Requirements Driving New Share Supply
The core of Jones’s concern centers on the immense capital needed to scale artificial intelligence infrastructure. Training massive models, expanding chip production, securing reliable energy, and constructing advanced data centers require multi-billion-dollar investments. To fund these expensive builds, prominent private firms and public corporations are turning to equity markets.
Jones highlighted anticipated initial public offerings from major artificial intelligence companies like Anthropic and OpenAI. He also noted SpaceX’s recently completed transaction as a clear example of incoming share supply. In addition to primary listings, public technology firms are expected to launch secondary share offerings to sustain their ongoing AI infrastructure spending.
Drawing Parallels to the Dot-Com Era
To put the coming market environment into perspective, Jones compared the current setup to the period leading into the dot-com bubble burst. Heavy corporate issuance between 1998 and 2002 created persistent downward pressure. This made those years some of the easiest periods for short sellers due to continuous share unlocks.
“2027 is going to be really, really challenging for the stock market,” Jones told CNBC. “You’ve probably got the most negative flow picture for the U.S. stock market that we’ve had, say, since 2002.”
Initial enthusiasm surrounding artificial intelligence has more than doubled the S&P 500 since the current bull market began. Even so, Jones cautioned that the sheer volume of new stock entering the market could overwhelm passive and institutional demand.
Macroeconomic Pressures and Portfolio Strategy
Beyond equity issuance, investors are navigating a complicated macroeconomic landscape. This landscape features persistent inflation concerns, higher bond yields, and a shifting Federal Reserve policy. Jones also revealed that he maintains a long position in oil. He predicted another significant rally following the midterms-a scenario he noted the stock market would strongly dislike.
As structural market dynamics transition from shrinking equity supply to an expanding float, everyday investors and portfolio managers may need to rethink their concentration in heavily valued technology names. Companies relying on steady internal cash flow to fund growth without diluting shareholders could hold a distinct advantage over those forced to repeatedly tap the equity markets.