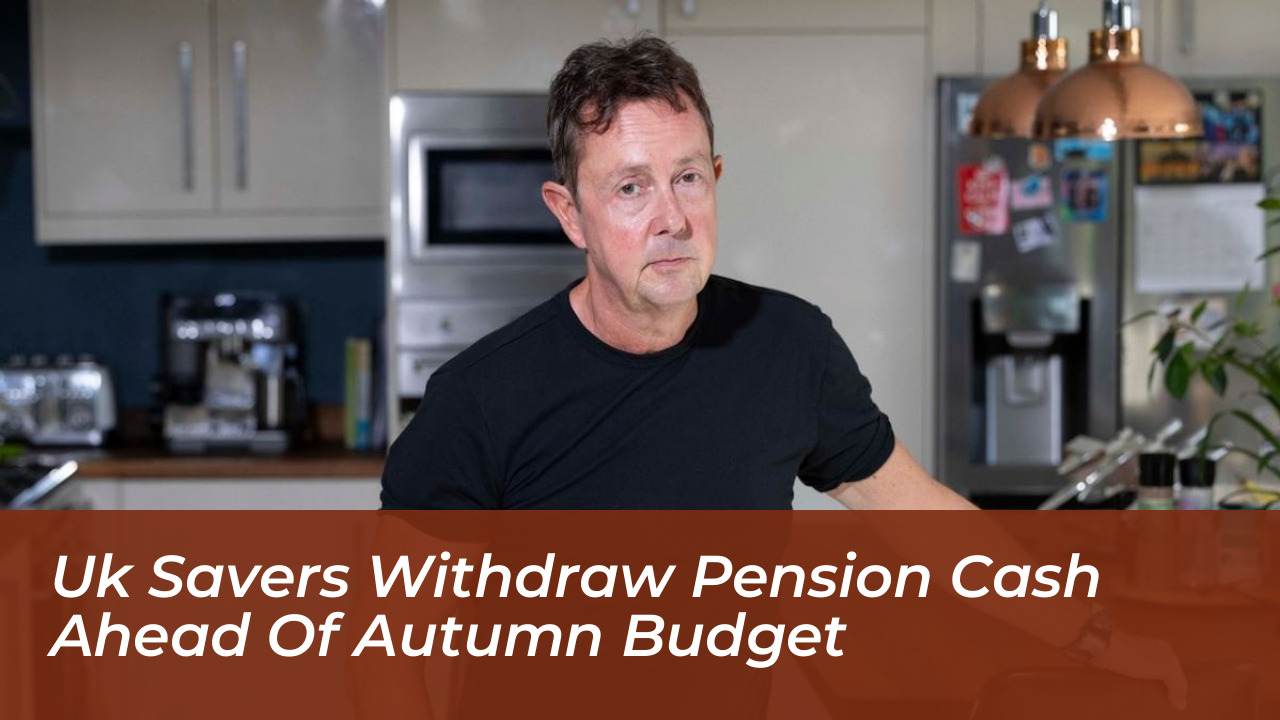

Uncertainty surrounding the United Kingdom’s upcoming Autumn Budget has prompted a growing number of savers to reconsider their retirement funds, inheritance plans, and long-term investments. As households prepare for potential tax modifications by the government, British wealth managers are reporting a sharp rise in early pension lump-sum withdrawals driven largely by pre-budget anxiety.
James Harrison, a 55-year-old freelance consultant from Surrey, recently withdrew his tax-free pension lump sum earlier than originally planned due to concerns that ministers might alter the rules. Harrison noted that his decision stemmed strictly from fears surrounding government policy shifts rather than an immediate need for the funds. “I would have been perfectly happy to leave it invested,” Harrison explained to reporters, echoing the sentiment of many retirement savers across the country who feel compelled to act before official announcements are made.
Surge in Lump-Sum Withdrawals Across Wealth Managers
Major financial institutions and wealth management firms have recorded significant spikes in customer inquiries and withdrawal requests. Private bank Arbuthnot Latham reported that pre-budget anxiety pushed client withdrawals to record levels, marking a 300% increase by volume year-to-date compared with the entirety of the previous year. Similarly, provider AJ Bell noted that its volume of requests to withdraw pension cash doubled and tripled over compressed autumn periods compared to historical baselines.
Data from Evelyn Partners highlights the broader scope of this trend, revealing that between April 2024 and March 2026, approximately £40.38 billion was withdrawn in tax-free cash lump sums-representing a 109% increase over the preceding two-year period. Financial Conduct Authority (FCA) data similarly confirmed that total flexible pension withdrawals had surged significantly in the months leading up to major fiscal policy announcements.
The Debate Over the 25% Tax-Free Allowance
Under current UK regulations, most defined contribution pension savers can access up to 25% of their retirement pot tax-free once they reach the minimum pension age, which is currently 55 and scheduled to rise to 57 in April 2028. The standard lump sum allowance is capped at £268,275 for those without historic protections.
However, speculation has repeatedly surfaced suggesting that the government could target this relief to help repair public finances. Think tanks, including the Institute for Fiscal Studies, have previously pointed out that the £5.5 billion annual cost of tax-free lump sums disproportionately benefits wealthier households. While ministers have not confirmed any plans to scrap the 25% entitlement or lower the existing monetary cap, persistent rumors have been enough to spur preemptive action among anxious savers.
Risks of Premature and Unplanned Withdrawals
Financial authorities and independent advisers strongly caution against making hasty financial decisions based purely on budget rumors. Research published by consumer groups indicates that a substantial majority of retirees who rush to access pension cash early ultimately regret the move. Removing money from a tax-efficient environment can expose future returns to income tax, capital gains tax, and inflation, potentially diminishing long-term living standards in retirement.
, experts warn savers about strict regulations regarding pension recycling. HMRC rules prevent individuals from taking a tax-free lump sum and quickly reinvesting large amounts back into a pension to claim double tax relief. Savers who violate these provisions risk facing severe tax penalties that can neutralize any perceived financial advantage.
Upcoming Pension Tax and Estate Reforms
While the 25% tax-free lump sum remains intact under current HMRC guidelines for the 2026/27 tax year, other significant structural changes are formally approaching. Most notably, from April 2027, unused pension funds and death benefits are scheduled to be brought within an individual’s estate for Inheritance Tax purposes. This upcoming modification represents a major shift in how generational wealth can be passed down, creating separate incentives for estate planning that should not be confused with day-to-day pension drawdown rules.
As the Treasury prepares its official fiscal statements, pension providers and industry executives continue to urge the government to provide clear, long-term certainty to prevent unnecessary disruption and protect retirement savers from making irreversible financial mistakes driven by speculation.
Frequently Asked Questions
Can the government completely scrap the 25% tax-free pension lump sum?
While commentators frequently speculate on potential reforms during every budget cycle, the 25% tax-free lump sum remains fully available under current HMRC rules, up to the standard limit of £268,275. Any official policy change would require formal legislation announced by the Chancellor.
What happens if I withdraw money from my pension early due to budget fears?
Withdrawing cash without a clear plan means your money leaves a tax-free growth environment. You may face immediate income tax on non-exempt amounts, miss out on future investment returns, and potentially run out of retirement funds sooner than planned.
Can I put my tax-free cash back into my pension if budget rules do not change?
HMRC enforces strict pension recycling rules to prevent individuals from taking tax-free cash and reinvesting it back into a pension to gain extra tax relief. Attempting to do so outside permitted contribution limits can trigger severe tax penalties.
What is the Money Purchase Annual Allowance (MPAA)?
The MPAA is a reduced annual allowance that is triggered if you flexibly access taxable income from your defined contribution pension. Taking only your tax-free lump sum generally does not trigger the MPAA, allowing most standard earners to continue contributing up to £60,000 per year subject to earnings.
When does the minimum pension age change?
The normal minimum pension age-the age at which most people can access their defined contribution pensions without unauthorized payment charges-is scheduled to rise from 55 to 57 starting on April 6, 2028.