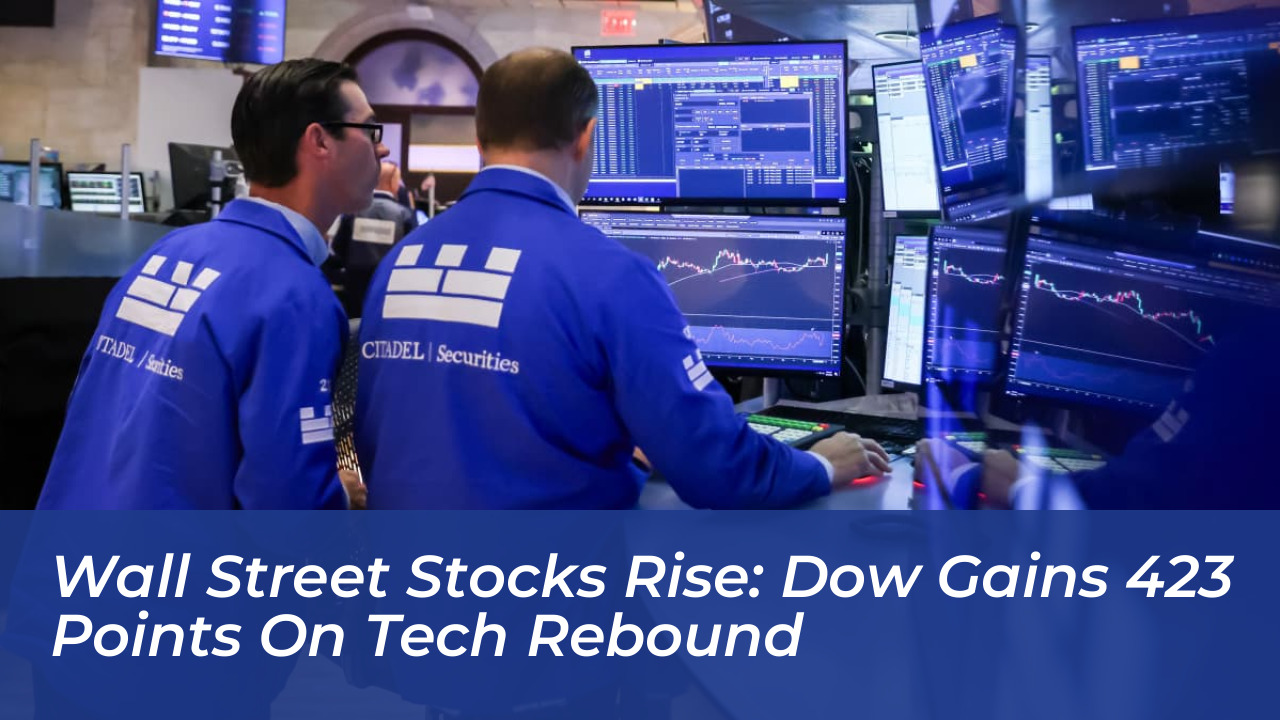
U.S. stocks climbed on Friday, October 9, 2026. Technology and healthcare shares recovered from recent losses. This helped Wall Street finish the week higher despite elevated Treasury yields, volatile oil prices, and ongoing concerns about artificial intelligence investments. The Dow Jones Industrial Average led major indexes, gaining 423.31 points as investors assessed energy supply developments and upcoming corporate earnings prospects.
The Dow rose 0.83% to close the session at 51,654.95, while the S&P 500 advanced 0.59% to end at 7,811.54. The Nasdaq Composite gained 0.64%, finishing at 27,366.17, according to CNBC closing reports. Over the five-day trading period, the Dow increased 0.9%, the S&P 500 rose approximately 1.2%, and the Nasdaq advanced 0.6%.
Technology and Healthcare Lead Friday’s Recovery
Technology shares spearheaded Friday’s market recovery following a difficult session for artificial intelligence-related equities. Palo Alto Networks gained 5%, while CrowdStrike and Palantir Technologies advanced 4% and 5%, respectively. Among industry heavyweights, Microsoft Corp. (NASDAQ: MSFT) rose 2.38% to close at $535.07, and Amazon.com Inc. (NASDAQ: AMZN) added 3.29% to finish at $262.43.
The rebound followed broader scrutiny of artificial intelligence revenue projections and a bond-market selloff. These factors had previously raised questions about the cost of financing future growth. Healthcare stocks also strengthened during the session, with Merck and Gilead Sciences each climbing more than 2%. Meanwhile, health insurer Humana surged approximately 11.6% following encouraging quality ratings developments for its Medicare Advantage plans.
Energy Markets and Geopolitical Factors
Energy markets remained a central focus for traders as crude prices fluctuated. Brent crude remained above $104 a barrel and West Texas Intermediate hovered near $92 before easing slightly in post-settlement trading. Late-session market sentiment received an additional boost following statements from President Donald Trump regarding a proposed Russian diesel-supply agreement intended to bring relief to global fuel markets.
However, broader economic pressures persisted. The University of Michigan’s preliminary October consumer sentiment survey showed consumer sentiment falling to 46.3 from 48.1 in September. Year-ahead inflation expectations increased to 4.7% from 4.6%, while longer-run expectations rose to 3.5% from 3.4%, keeping consumer purchasing power and borrowing costs at the forefront of investor concerns.
Treasury Yields and Upcoming Corporate Earnings
Bond market conditions continued to present a challenging backdrop for equities. The benchmark 10-year Treasury yield hovered near 5.24%, reflecting lingering inflation worries and the possibility of higher-for-longer interest rates. Elevated yields continue to influence corporate financing costs and consumer lending rates across mortgages and other credit products.
Looking ahead, Wall Street is turning its attention to the upcoming third-quarter reporting season. Major financial institutions, including JPMorgan Chase, Citigroup, Wells Fargo, and Goldman Sachs, are scheduled to report quarterly earnings. These reports will provide critical insights into consumer borrowing, credit quality, and overall economic health. Additionally, upcoming September Consumer Price Index (CPI) and Producer Price Index (PPI) reports will offer further direction for the Federal Reserve’s monetary policy outlook.
- Dow Jones Industrial Average: Gained 423.31 points (+0.83%) to close at 51,654.95.
- S&P 500: Advanced 46.18 points (+0.59%) to finish at 7,811.54.
- Nasdaq Composite: Added 172.83 points (+0.64%) to end at 27,366.17.
- Weekly Performance: S&P 500 up 1.2%, Dow up 0.9%, and Nasdaq up 0.6%.